Market overview of the Oil Downstream Products Market
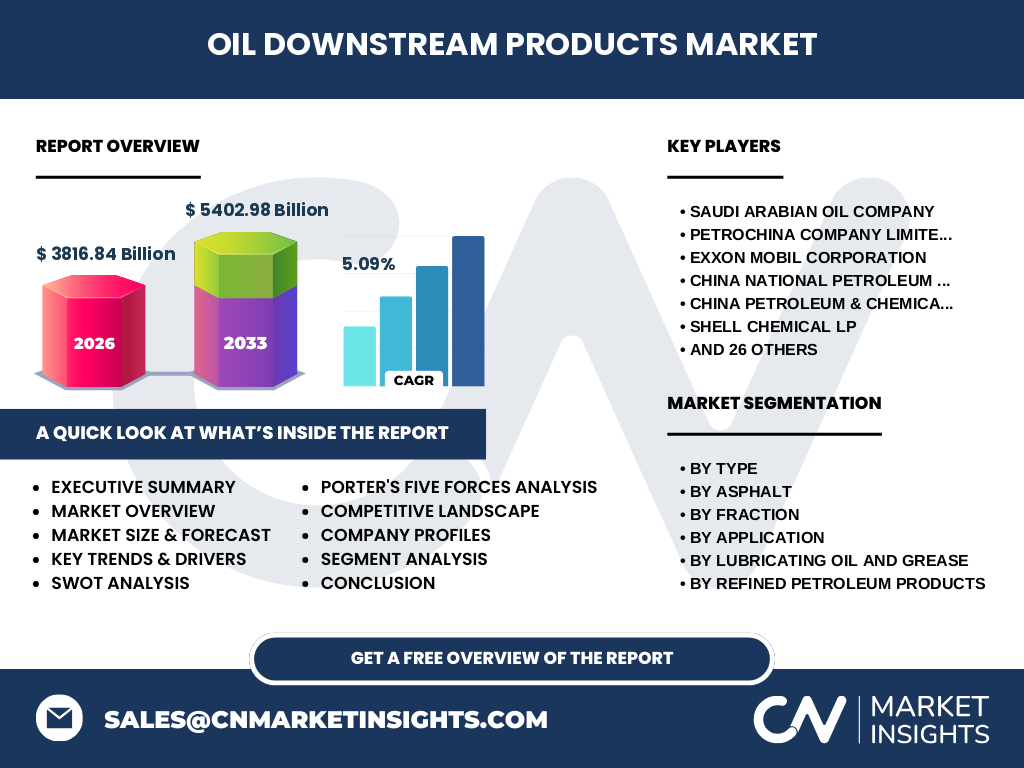
Our analysis indicates that the Oil Downstream Products Market is valued at $3,816.84 Billion in 2026, serving as the critical refining and distribution bridge between crude extraction and end-user consumption. Operating under strict environmental mandates from bodies like the EPA and EU directives, the industry converts crude oil into high-value commodities via complex fractional distillation and catalytic cracking at strategic refining hubs worldwide.
What are the core market drivers, restraints, challenges, and opportunities in the Oil Downstream Products Market?
Growth is propelled by expanding chemical feedstock demand and emerging-market urbanization, though tightened sulfur regulations and volatile crude supply chains act as key restraints. Refiners face logistical hurdles moving heavy oils and hot mix asphalt through congested marine terminals. Strategic opportunities lie in upgrading middle distillate yields to jet fuel and low-sulfur diesel to capture higher margins.
Emerging trends and growth patterns in the Oil Downstream Products Market
The shift toward petrochemical integration is redefining refinery economics, moving away from pure fuel production toward value-added chemical feedstocks. Industry leaders like Saudi Aramco and Sinopec are modernizing assets to maximize light distillates conversion, driven by surging regional demand for specialized polymers and industrial lubricants.
COVID-19 impact analysis and recovery trajectory
The pandemic caused an unprecedented demand collapse for jet fuel and gasoline, forcing unplanned downstream capacity rationalization. Recovery has been propelled by robust post-lockdown mobility rebound and inventory destocking, enabling refiners to rebuild margins despite persistent supply chain friction and fluctuating regional energy costs.
Competitive benchmarking and strategic dynamics in the Oil Downstream Products Market
Market concentration remains high among vertically integrated national oil companies and supermajors like ExxonMobil, Shell, and TotalEnergies. Competitive advantage increasingly relies on complex refining configuration indices, feedstock flexibility, and carbon-reduction technologies designed to comply with tightening international environmental standards.
Executive summary of the Oil Downstream Products Market research report
Our research forecasts the Oil Downstream Products Market to expand from $3,816.84 Billion in 2026 to $5,402.98 Billion by 2033 at a steady CAGR of 5.09%. Profitability will increasingly favor operators capable of pivoting seamlessly between refined fuels and petrochemical feedstocks.
Long-term market forecast from 2027 to 2033
Driven by expanding industrial output across developing economies, the market is projected to scale from $3,816.84 Billion in baseline evaluations to reach $5,402.98 Billion by 2033. This trajectory reflects a steady CAGR of 5.09%, underpinned by rising consumption of specialty lubricants and petrochemical derivatives.
Segmentation analysis across product types and fractions
The market is categorized by Type (Refined Petroleum Products, Asphalt, Lubricating Oil And Grease), Fraction (Light Distillates, Middle Distillates, Heavy Oils), and Application (Fuel, Chemical, Other Applications). Refined products split further into gasoline, diesel, jet fuel, and petrochemical feedstocks, while asphalt covers hot mix, cutback, and emulsified variants.
Regional market analysis and geographic performance
Asia-Pacific dominates consumption, powered by refining expansions in China and India, while North America and Europe prioritize high-complexity upgrading to meet strict environmental specifications. Middle Eastern producers leverage low-cost feedstock advantages to export refined middle distillates to key international maritime hubs.
In-depth regional review of key markets
Asia-Pacific leads volume growth due to rapid industrialization and massive petrochemical capacity additions by players like PetroChina and Reliance Industries. Meanwhile, North American refiners such as Valero and Marathon Petroleum focus on heavy crude processing optimizations to maximize diesel and jet fuel export yields.
Company profiles and strategic positioning of leading participants
Industry titans like Saudi Arabian Oil Company, Exxon Mobil Corporation, and Royal Dutch Shell command vast market share through highly integrated refining-petrochemical complexes. Regional powerhouses like Indian Oil Corporation and Rosneft maintain dominant domestic distribution networks while expanding export capabilities into high-demand corridors.
Porter's Five Forces analysis of the downstream sector
Bargaining power of suppliers is moderate due to diverse crude sourcing options, whereas buyer power is high for standard commercial fuels. Threat of substitutes remains constrained in aviation and heavy industry, though intense rivalry among major refiners compels continuous margin optimization and technological upgrading.
SWOT analysis of the Oil Downstream Products Market
Strengths lie in established global distribution networks and complex conversion capabilities. Weaknesses involve high capital expenditure requirements for environmental compliance. Opportunities center on advanced petrochemical integration, while threats include accelerated regulatory decarbonization mandates and volatile crude oil pricing.
Value chain analysis from raw materials to end-users
The value chain originates with crude oil extraction, moving through primary distillation, secondary catalytic conversion, and blending processes. Finished products flow via pipelines, tankers, and rail terminals to end-use sectors including transportation fuel, asphalt paving, and chemical manufacturing facilities.
Investment insights and high-potential growth areas
High-potential capital allocation targets include hydrocracking units designed to maximize diesel and petrochemical feedstocks, as well as specialty lubricant blending facilities. Investors should prioritize integrated players demonstrating lower carbon intensity per barrel of refined output.
Conclusion and strategic takeaways for industry stakeholders
Sustained success in the downstream sector requires navigating a CAGR of 5.09% through strategic asset flexibility. Companies must balance traditional fuel output with advanced chemical feedstock production to safeguard profitability against shifting global energy demand patterns.
Research methodology and data triangulation practices
Our baseline estimates are established by triangulating international trade registry data, primary executive interviews with refinery operators, and secondary macroeconomic indicators. This multi-layered approach reconciles national energy balances with proprietary bottom-up facility throughput models.
Scope of the report and analytical boundaries
This report covers global downstream processing trends, encompassing all major fractions, asphalt variants, and lubricating oil segments from 2026 through 2033. Excluded from primary scope are upstream exploration and retail station forecourt operations not directly tied to refinery gate economics.
Recent developments, partnerships, and strategic moves
Recent industry activity highlights major joint ventures in petrochemical-refinery integration across Asia and the Middle East. Companies like TotalEnergies and BP are actively divesting legacy high-emission assets while channeling capital into advanced recycling and low-carbon lubricant formulations.